The complete document checklist
For sole proprietors and incorporated owners.
For self-employed borrowers
Prepare the documents lenders review, understand how business income is assessed and avoid five common approval mistakes. Includes information about insured self-employed programs and a planning timeline.
Elena Bogomaz
CPA | Mortgage Professional
Mortgage advice that starts with the full financial picture, not the advertised rate.
Five practical pieces that help turn tax documents and business income into a clearer mortgage strategy.
For sole proprietors and incorporated owners.
Including which eligible expense adjustments, often called add-backs, may count.
Choices that can shrink or stop an application.
Insured options for eligible borrowers, including insurer and lender requirements.
Understand whether you have options today and what preparation could help your next application.
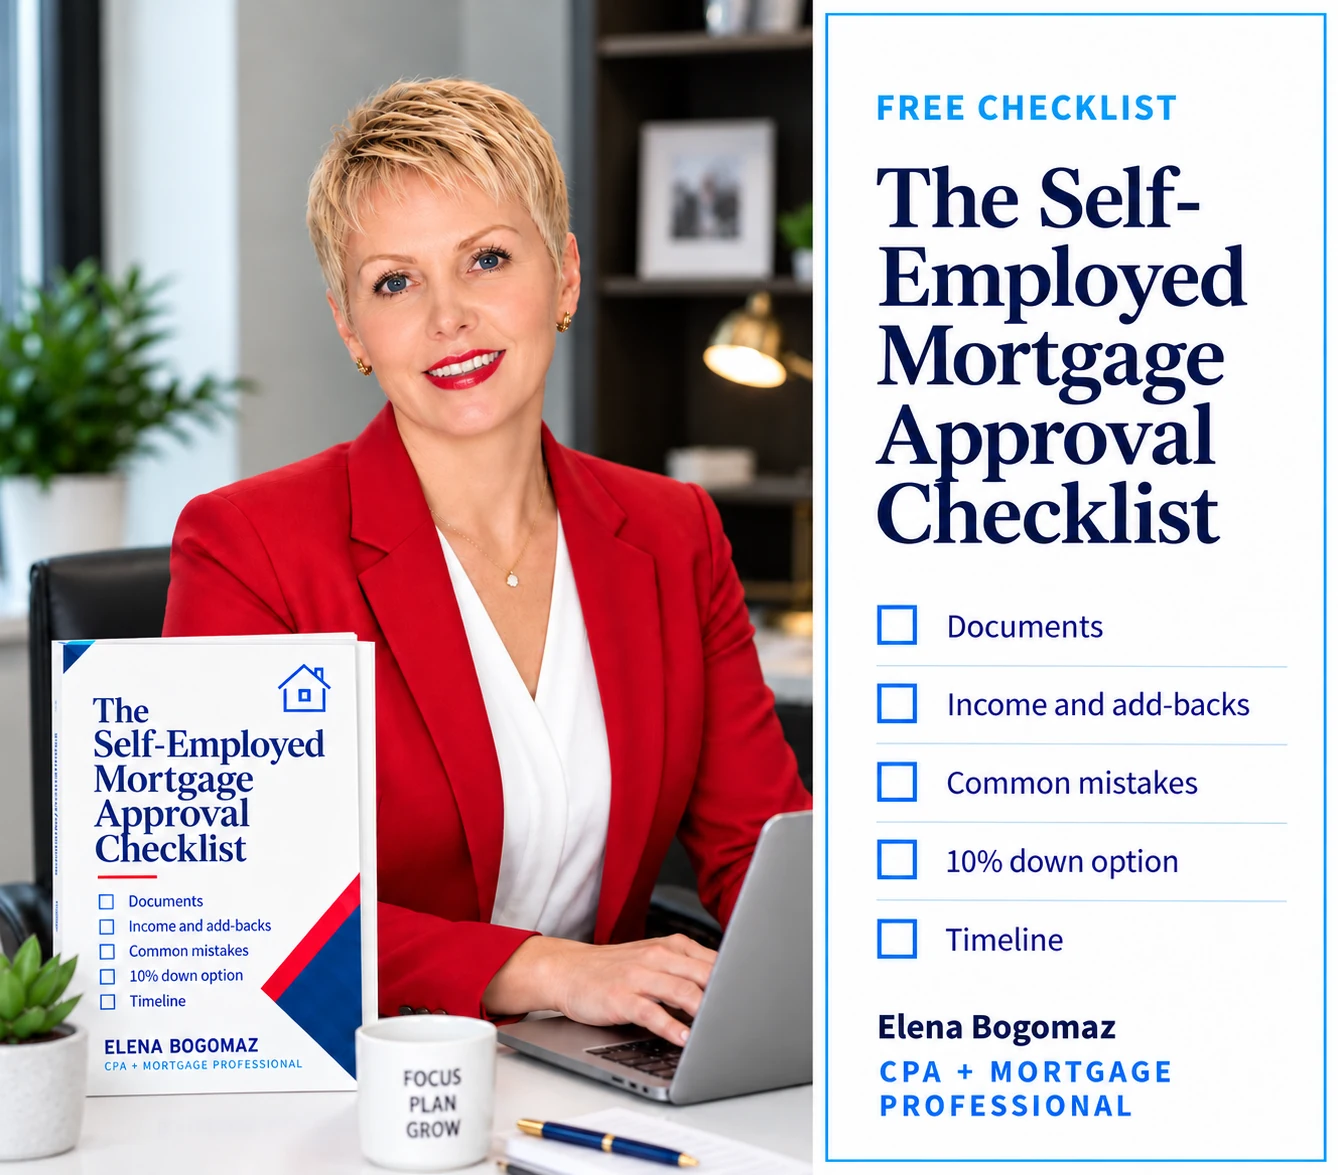
Written by Elena Bogomaz, CPA | Mortgage Professional. She reads the tax documents banks skim over and looks at income, corporate structure, cash flow and qualification together.
Some of her clients were approved for $200,000 to $300,000 more after their bank had approved them for less. Past results are not a guarantee, but they show why the right analysis matters.
Meet ElenaReview qualification, cash flow, taxes, penalties and future plans before choosing a structure.